Keys change hands at noon, and the moving truck shows up Saturday. That gap of four days living in a house somebody else now owns is one of the most common requests I hear from Connecticut homeowners. It’s completely workable if you set it up right. Some people call it a rent-back, and attorneys call it a post-closing occupancy agreement. The question underneath never changes. How long can a seller stay in the house after closing before somebody’s loan, insurance, or patience breaks?
What Happens on the Day You Hand Over the Keys
You might think the whole thing is a technicality, that nobody’s going to show up with a moving crew while your couch is still in the living room. In Connecticut, closing is the moment legal title transfers. The buyer’s rights kick in that same afternoon unless a signed document says otherwise.
Your attorney and the buyer’s attorney exchange documents, funds move, and the warranty deed gets recorded at the town clerk’s office. Once that deed hits the land records, the buyer owns the walls, the roof, and the driveway. Staying after closing without paperwork leaves you an occupant with no clear legal standing.
Connecticut handles closings differently from a lot of states. We’re an attorney state, so a licensed Connecticut attorney conducts the closing. That gives you a real advantage if you want to stay after closing, because a lawyer drafts your occupancy terms instead of a settlement clerk working from a form.
Last year I bought a colonial in Wethersfield from an out-of-state heir. She was also splitting assets in a divorce and wanted the sale handled, nothing more. The garage still held her late father’s snowblower and about forty paint cans. We wrote a short occupancy window into the contract so her brother could clear the place on a weekend, and the sale closed without anyone driving up from Virginia twice.
Does possession have to transfer at closing in Connecticut? No, and it often doesn’t when a seller is selling during a divorce or an estate sale. It transfers when the two parties agree it does, as long as that agreement exists in writing before the ink dries.
What to Expect When Signing the Closing Package in Connecticut
Sit down with me and I’ll tell you what I tell everyone at a kitchen table in Bristol. Read the possession clause before you read anything about money. That one paragraph decides whether you sleep in your own bed the night after closing.
The Connecticut closing package runs long. You’ll sign the deed, a conveyance tax return for the state and the town, a title affidavit, and payoff authorizations for any mortgages on the property. If you’re staying after closing, there’s one more document, separate from the purchase contract, spelling out your occupancy terms. Our list of documents needed to sell covers the rest of the stack.
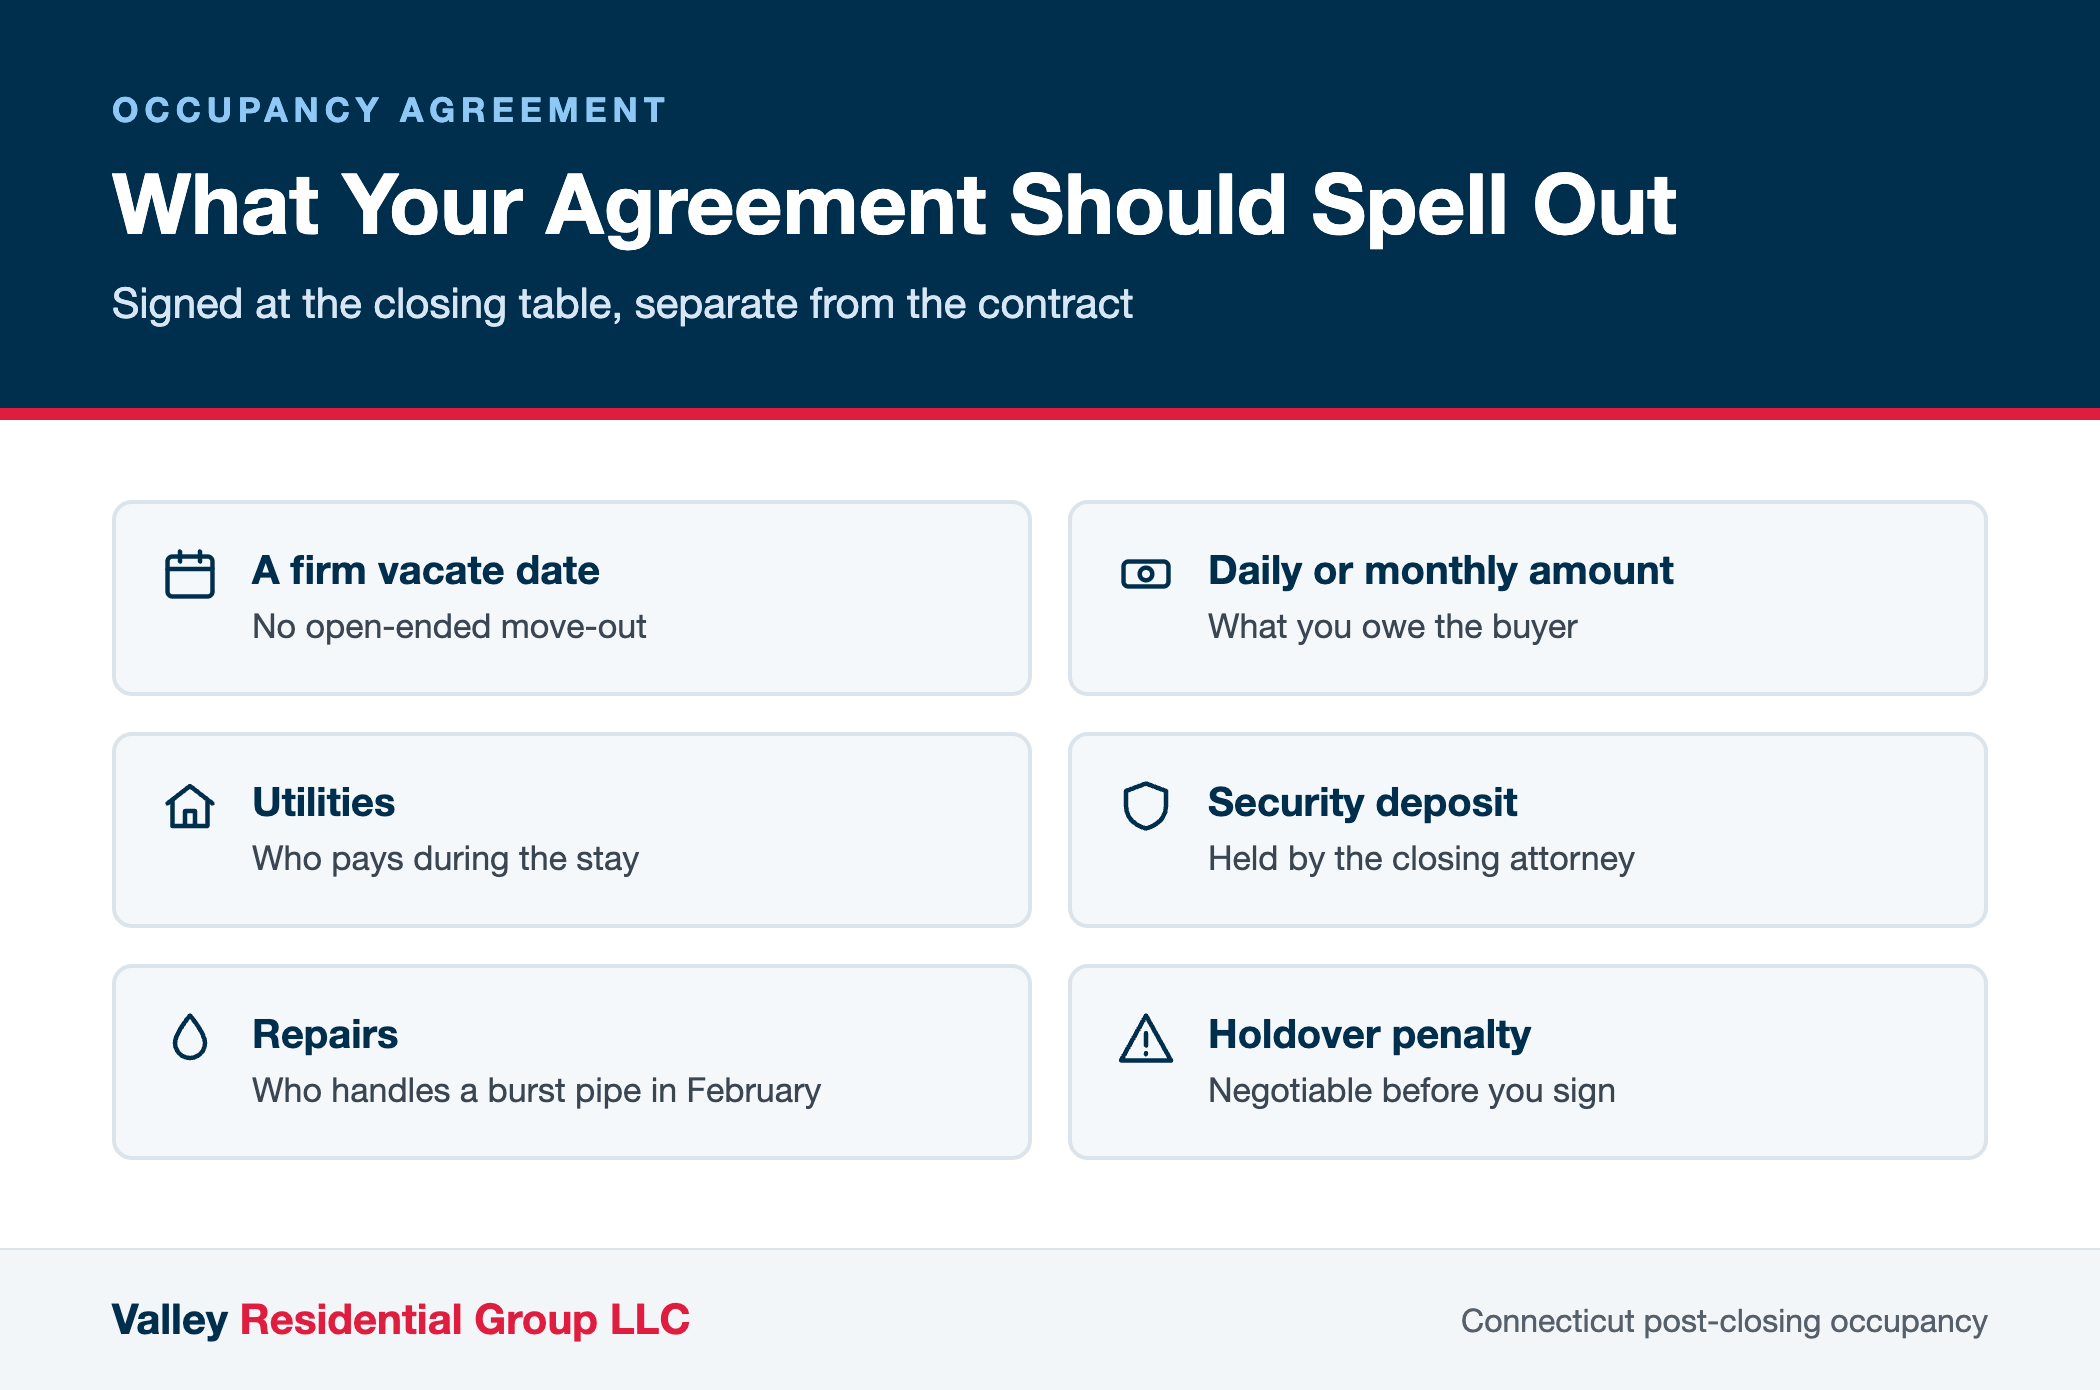
Many sellers underestimate how much that separate agreement matters. A possession clause buried in the sales contract gets fuzzy once the contract merges into the deed. A standalone occupancy agreement stays enforceable on its own terms, and you sign it at the Connecticut closing table with everything else.
Ask your attorney to confirm the document covers a firm vacate date, the daily or monthly amount you owe, and who pays utilities. Confirm what happens to the security deposit, too, and who handles a burst pipe in February.
Connecticut real estate attorneys usually draft these in an afternoon. The cost is small next to what a fight over an undefined move-out date runs.
One pattern keeps repeating. Sellers negotiate hard on price for six weeks, then sign the occupancy terms for the weeks after closing without reading them, because they’re exhausted and the conference room is warm. Slow down on that page. It’s the only one that governs where you actually live.
What Happens to Your Mortgage After Closing
Maria sold her Hartford colonial on a Friday and still made dinner in the same kitchen that night, owing her lender nothing. The closing attorney wires the payoff to your lender from the sale proceeds, and the mortgage release gets recorded on the Connecticut land records within a few weeks. Staying after closing doesn’t keep the loan alive. Our guide to selling with an existing mortgage walks through the payoff side.
Your other obligations end right along with the loan, even during occupancy. You can be living in a Connecticut house with zero mortgage obligation, zero property tax obligation, and zero ownership interest, all at once.
What does continue is your responsibility for the things you use. Electricity, gas, water, and internet usually stay in your name during the occupancy period, since the buyer doesn’t want to transfer accounts twice.
Insurance is where the real exposure sits, and sellers handle it worst. Your homeowners policy ends when you stop owning the home. The buyer’s policy covers the structure, not your furniture, your electronics, or your liability if your nephew slips on the back steps. Call your agent before closing and ask about a renters policy for the occupancy window after closing. It’s inexpensive, and it closes a real gap.
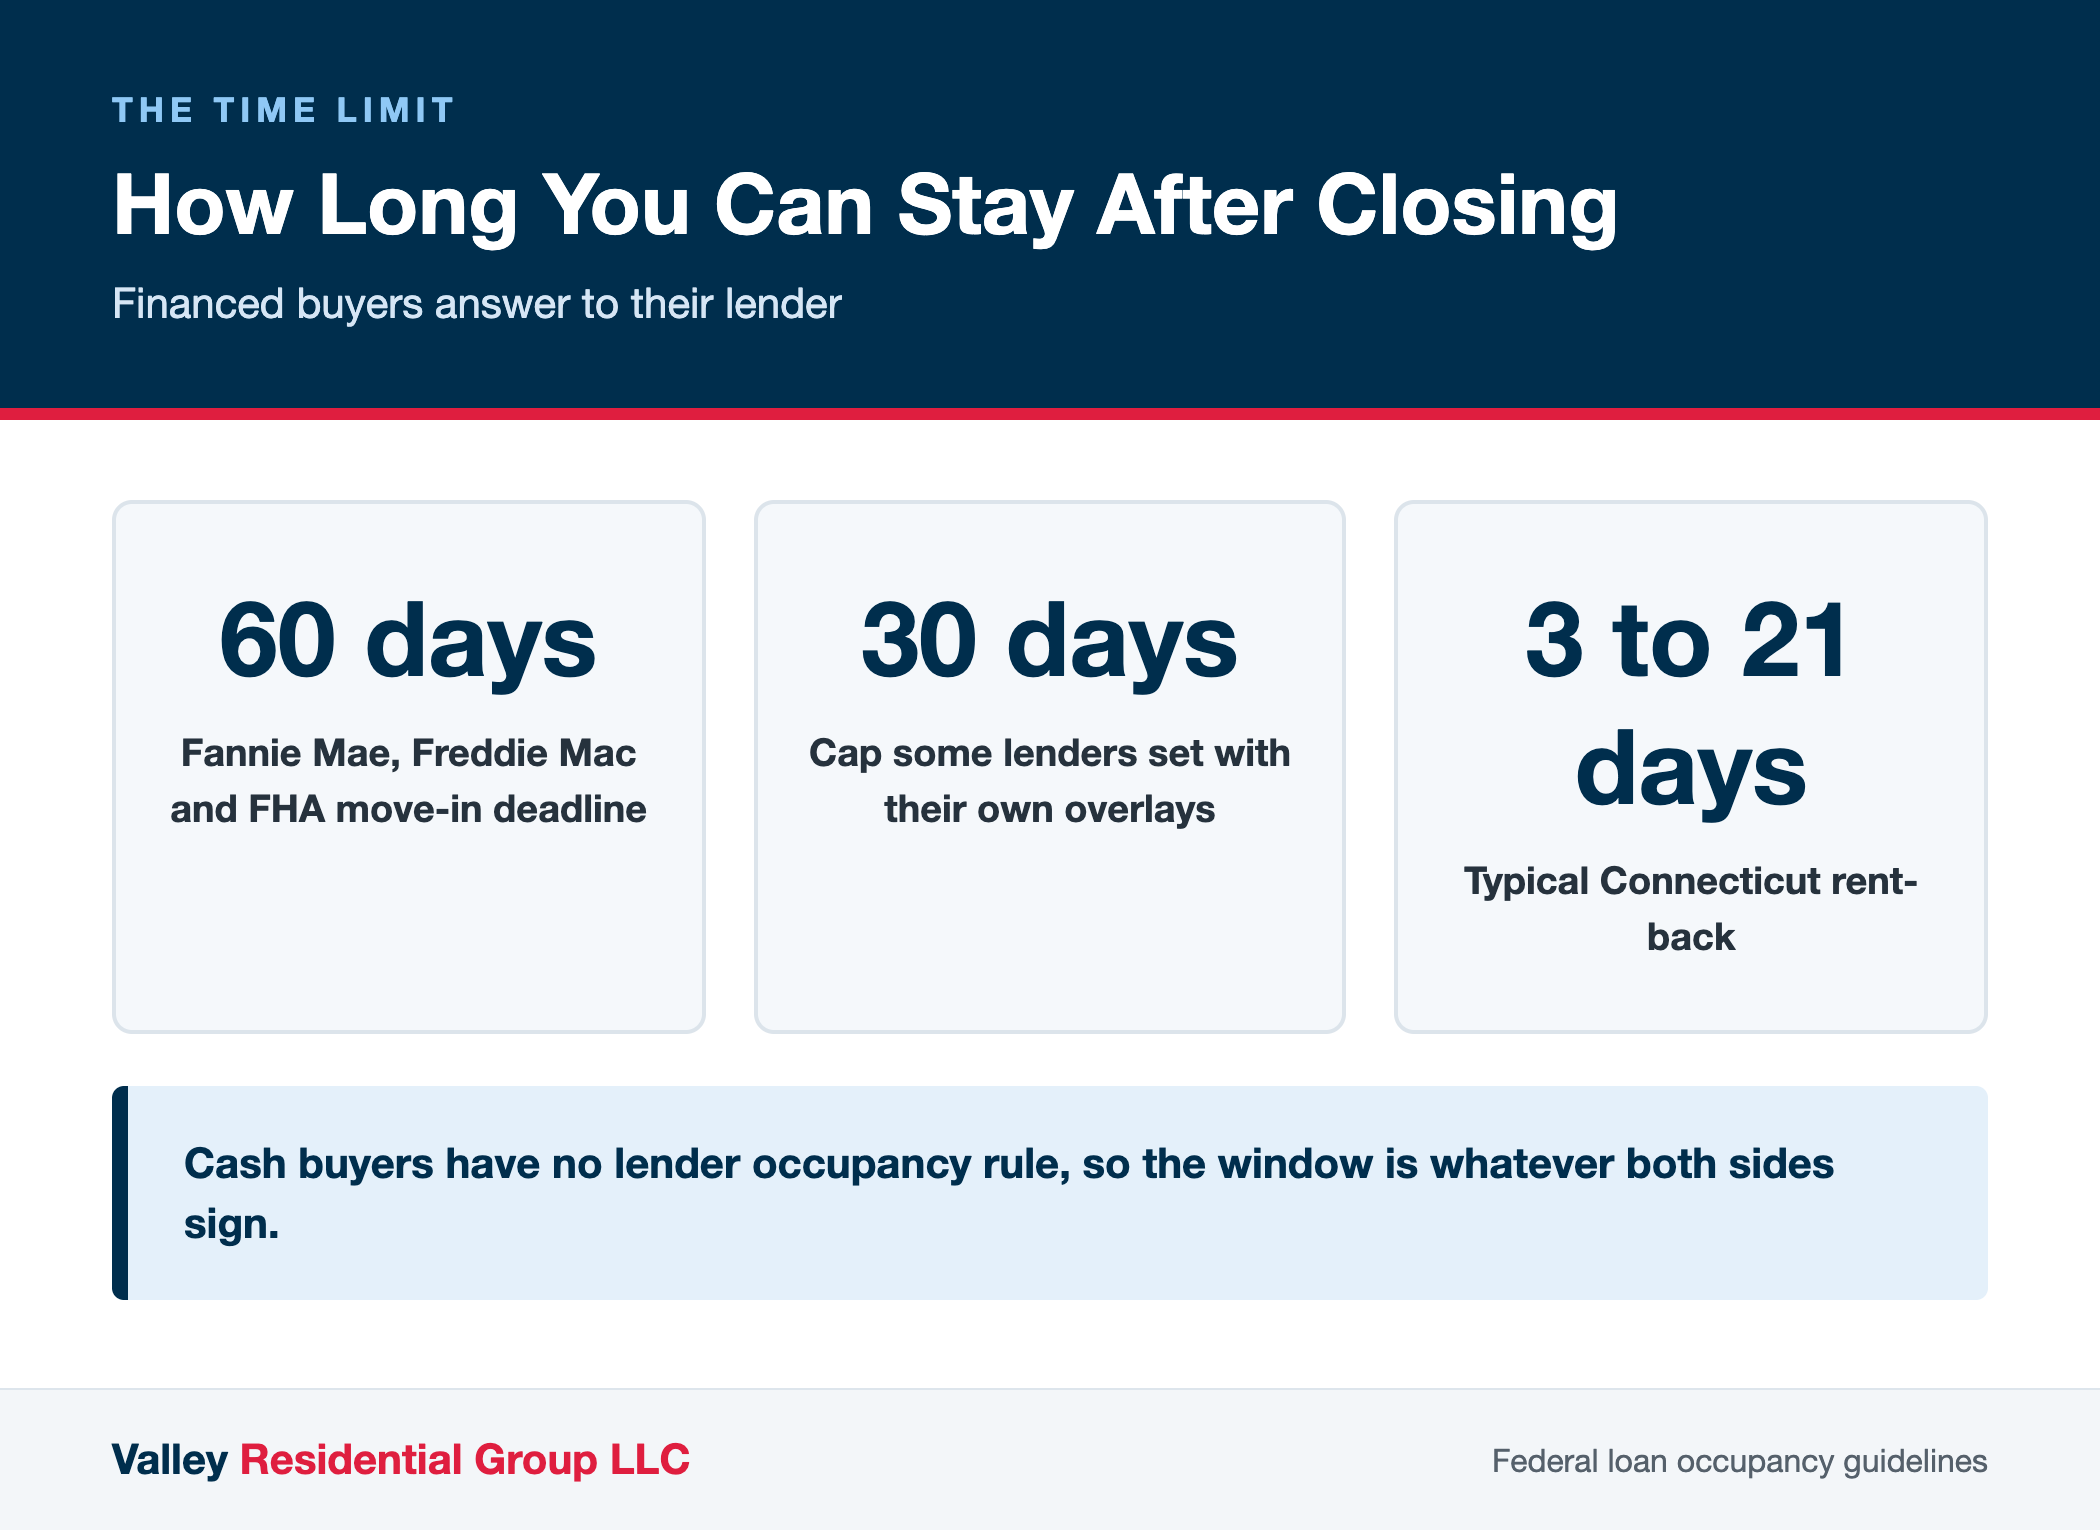
The buyer’s lender has opinions too, and those opinions set your ceiling. Fannie Mae, Freddie Mac, and FHA all require a buyer financing a primary residence to move in within 60 days of closing. A seller rent-back can run up to that deadline, though many lenders suggest capping it at 59 days. Jumbo borrowers face tighter rules, which matters in Fairfield County.
How Long Can a Seller Stay in the House After Closing in Connecticut
Sixty days is the outer wall for most financed sales. It isn’t a Connecticut rule at all. It’s a federal loan guideline that lands on every Connecticut transaction with a conventional or FHA mortgage. Some lenders add their own overlays capping rent-backs at 30 days, and jumbo programs tend to be stricter still.
Most Connecticut rent-backs I see run between three days and three weeks after closing. Sellers need a weekend, a closing date on their next house, or a school year to finish in Glastonbury.
Cash buyers change the arithmetic completely. No lender means no owner-occupancy covenant, so the only limit on how long a seller can stay after closing is whatever the two parties write down. I’ve set up 90-day occupancy periods on Connecticut sales where the seller was waiting on a new build in Simsbury.
Timing pressure is real statewide right now. A typical Connecticut listing spends 42 days on the market before it sells or gets withdrawn, as of October 2026. Redfin data put the state’s median sale price at $448,711 in September 2026. Add a month and a half of marketing to a 30-to-45-day financed closing, and you’re looking at a long runway before you need to be packed.
How much time do you really need after closing? Be honest with yourself, then add three days. Sellers underestimate the tail end of a move constantly, and a holdover penalty is a miserable way to learn that.
How Do You Get Paid When You Stay After Closing
A family in Manchester sold in March and needed 18 days to finish their daughter’s semester. They paid the buyer a daily rate that covered his carrying cost, and everybody moved on without one uncomfortable phone call.
The seller pays the buyer for occupancy after closing, not the reverse. In the standard setup, you pay a per diem covering the buyer’s principal, interest, taxes, and insurance, plus any condo or association dues.
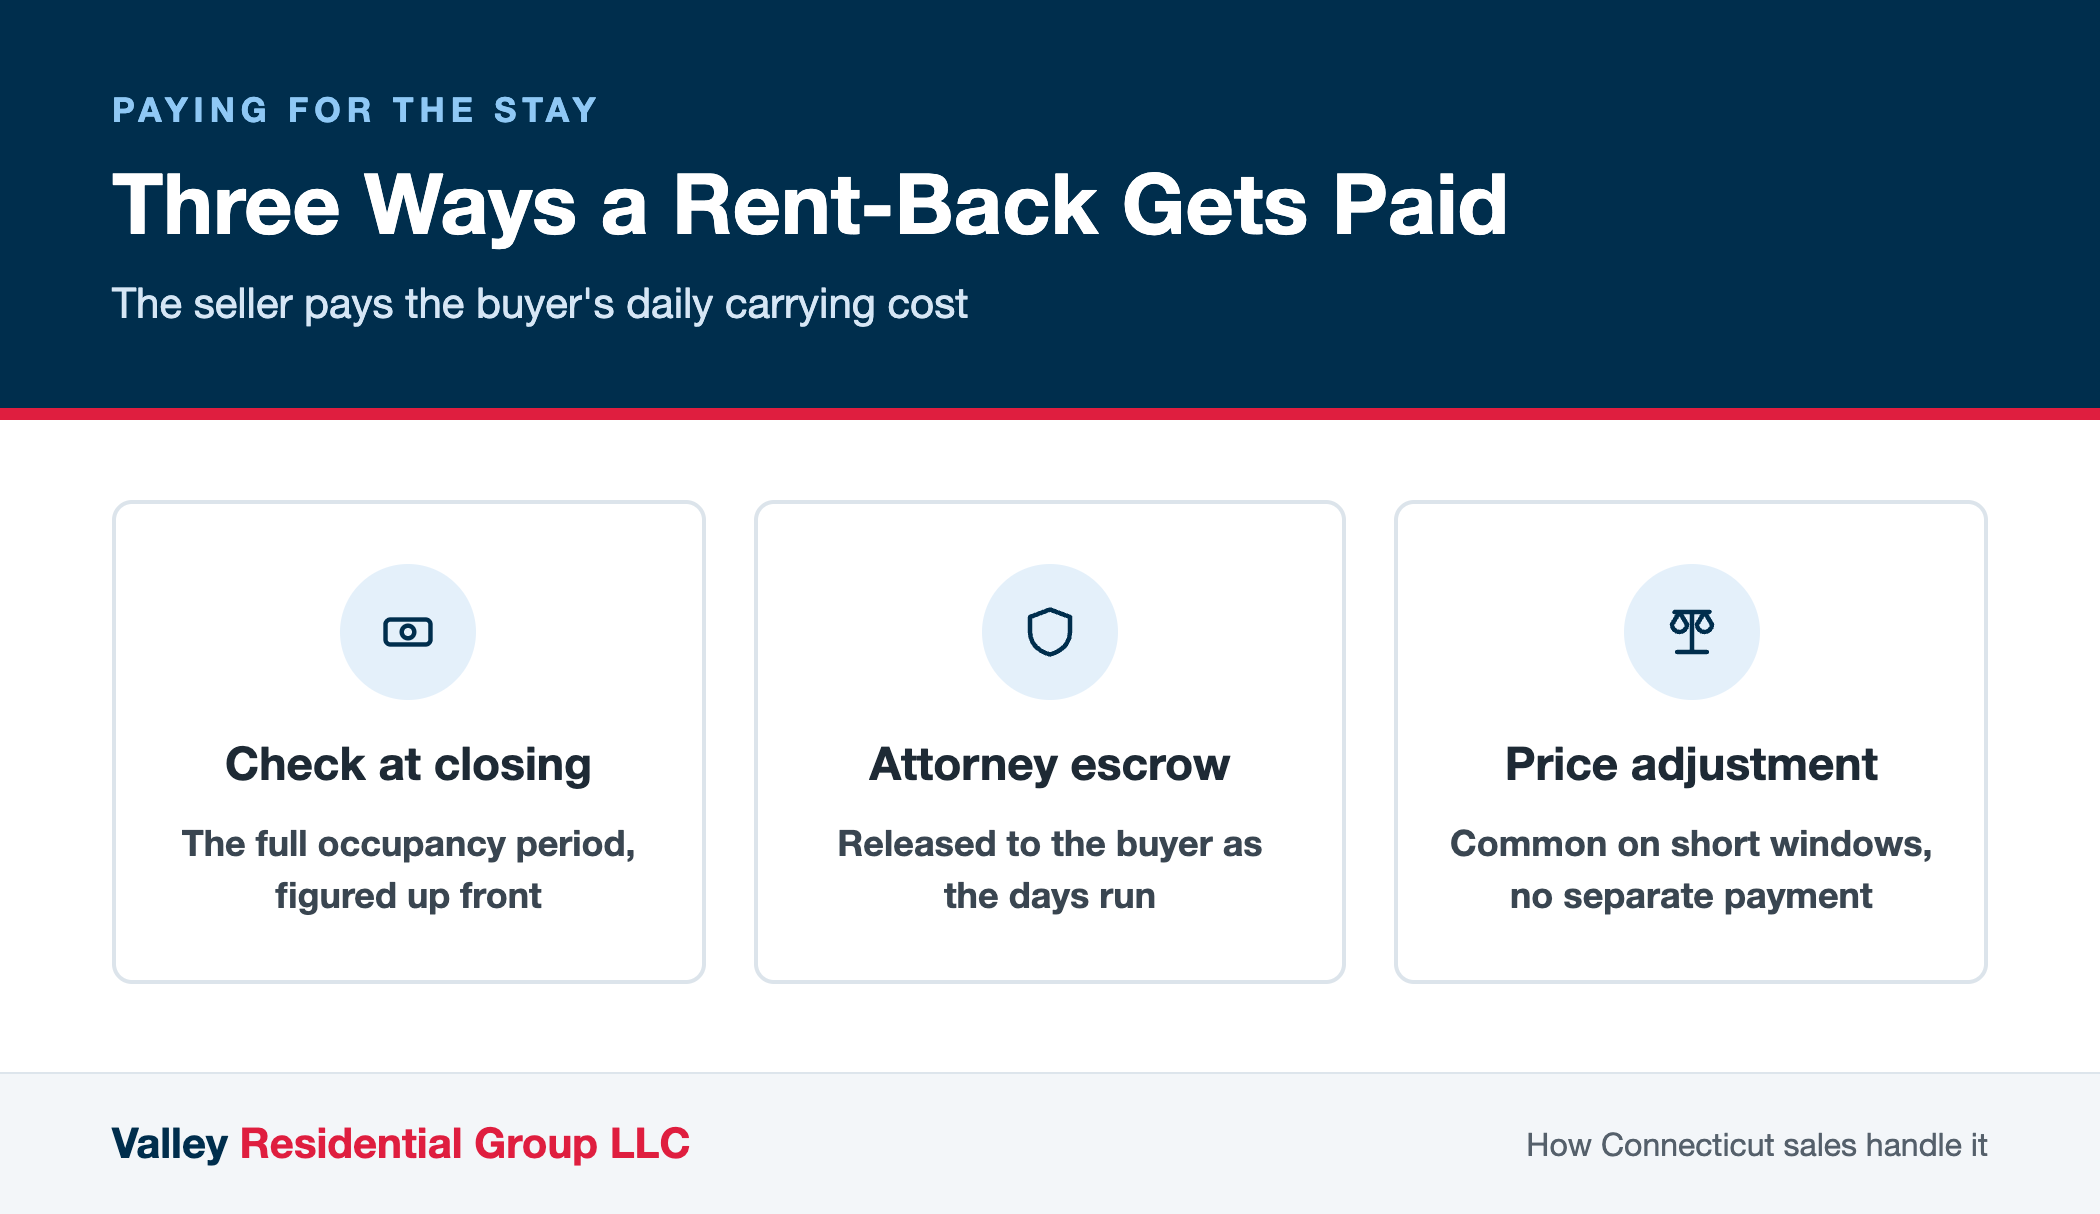
Connecticut sales usually handle it one of three ways. You can write a check at closing for the full occupancy period, figured up front. Your attorney can hold the amount in escrow and release it to the buyer as the days run. On short windows, the price sometimes gets adjusted and no money changes hands separately.
Free occupancy happens often on Connecticut sales under a week. A few days without payment is an easy concession when demand is this strong. If a buyer wants your house in a market where the single-family median hit $490,000 in September 2026, up 5.4% year over year, three days of free possession is cheap goodwill. I’ve waived short rent-backs plenty of times and never regretted a seller staying after closing.
Security deposits are a different conversation, and I’d push back on sellers who resist them. The buyer is handing you his new house and hoping he gets it back in the same shape. A deposit held by the closing attorney protects both sides, and you get it back at the walk-through.
Watch the holdover clause. Many agreements set a penalty rate several times the daily occupancy fee if you stay past the agreed date, and that number is negotiable before you sign.
What Risks Come with Staying in the House After Closing
The biggest risk isn’t money. It’s tenancy. Stay long enough in a Connecticut home after closing, paying monthly, and you may stop being a departing seller and become a tenant with statutory protections.
That cuts both ways. As the seller, those protections sound great. They also mean the buyer can’t legally make you leave without a legally sufficient ground for eviction and the court process known as summary process.
Connecticut’s eviction path isn’t quick. Under Connecticut General Statutes § 47a-23, the landlord must serve a written notice to quit giving the tenant at least three full days before a summary process action is filed. A court case in the Superior Court Housing Session follows. The Judicial Branch puts the minimum time for summary process to reach judgment at 30 to 45 days from service of the notice to quit. You can read its own walkthrough at the Connecticut Judicial Branch site.
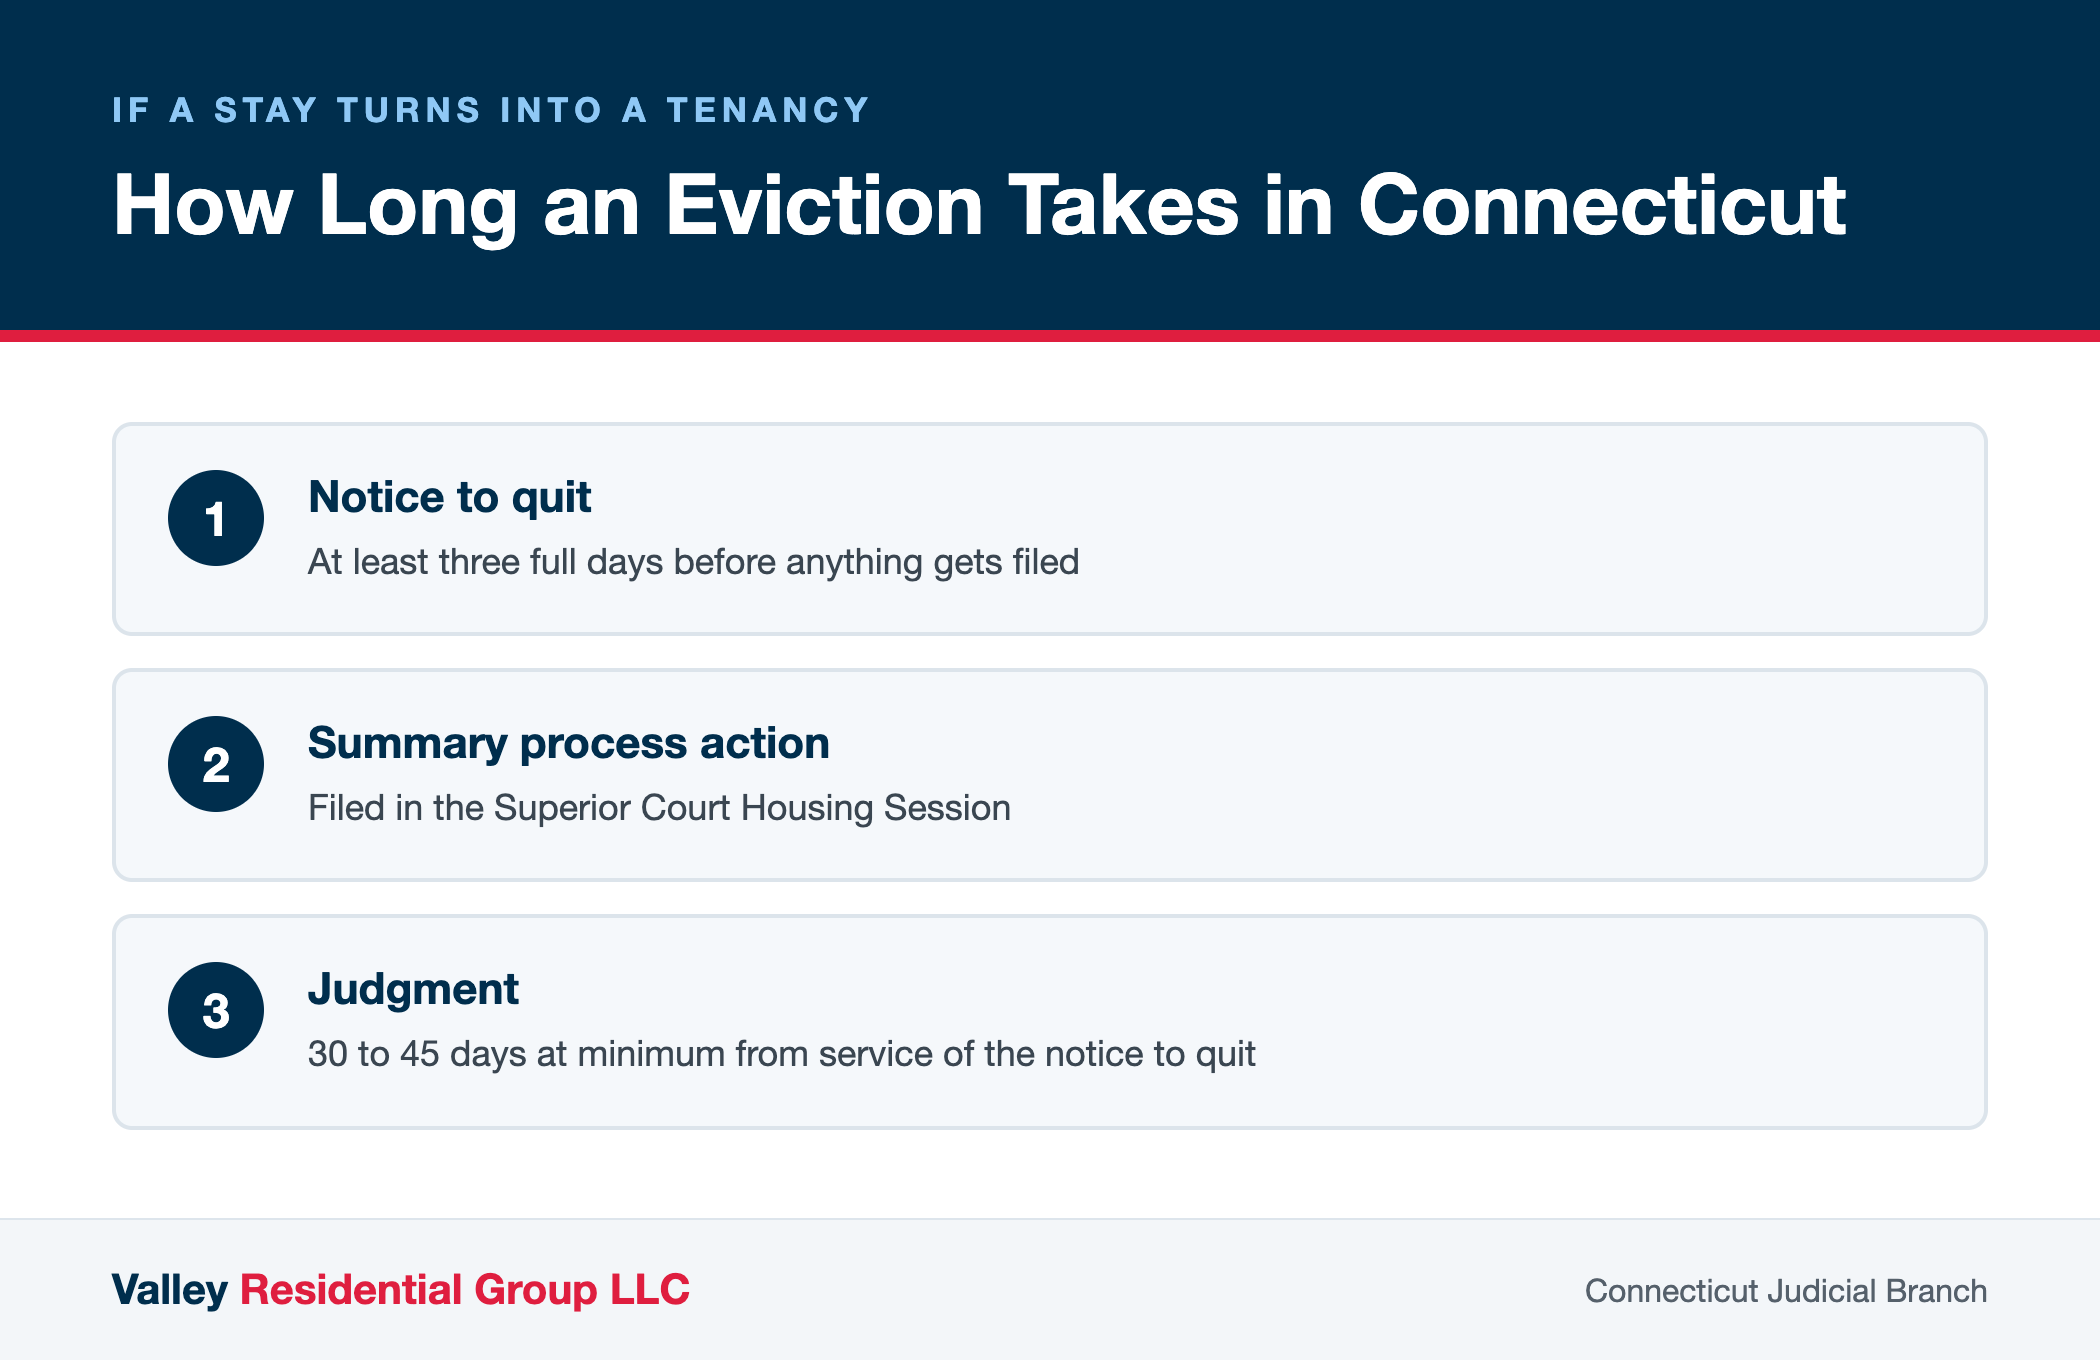
Keep the occupancy period short and the tenancy question never comes up.
Damage disputes are the other recurring headache. A scratched floor gets blamed on the seller during move-out, the seller swears it was already there, and the deposit sits in escrow while two attorneys trade emails. Dated photos taken at closing and again at move-out settle most of these arguments.
Then there’s the buyer’s financing risk. If the seller stays past the 60-day mark, the lender may reclassify the property as an investment, which can trigger a refinance requirement and a higher interest rate.
Does a Trusted Buyer Make Staying After Closing Easier
“Can I just stay until my mother’s place is ready?”
Ask that of a buyer with a mortgage commitment and a rate lock, and you’ll get a careful maybe. Ask a cash buyer and you’ll usually get a yes, because nothing in that buyer’s file cares when you leave.
A financed Connecticut buyer answers to an underwriter in another state. A local investor answers to himself, and he’s already decided the house is worth buying with you in it for a few more weeks.
So I point Connecticut sellers who need flexible timing toward buyers who can actually deliver it, since not every buyer is set up for that. Valley Residential Group LLC works throughout central Connecticut and writes occupancy terms into offers regularly for sellers who need breathing room after closing. The paperwork still gets done properly. There’s just no lender setting the calendar.
Flexibility isn’t free, and I’d rather say that plainly. A cash offer with a generous occupancy period usually comes in under what you’d get listing on the MLS. What you’re buying with that gap is certainty about dates.
Sometimes the retail listing wins even with the hassle. Other times a seller in Southington with a job starting in Charlotte on the first of the month runs the math, and the certainty wins outright.
What Questions Should You Ask Before You Agree to Stay After Closing
Any occupancy arrangement that isn’t in writing is a handshake you’ll regret.
Start with the buyer’s lender. Does the loan allow a rent-back at all, and for how many days? Get written confirmation from the loan officer, not a verbal assurance from an agent.
Then look at the document itself. Does it name a hard vacate date? What’s the daily rate, and is it prepaid or escrowed? Who’s responsible for the furnace if it quits on a January night in Torrington? What’s the holdover penalty, and does the agreement spell out what broom clean means at move-out?
Insurance comes next. Confirm in writing with your Connecticut agent that your contents and liability are covered during occupancy after closing.
Ask your closing attorney one more question. Does this agreement create a tenancy under Connecticut law? A short, fixed-term, prepaid occupancy usually doesn’t, but a monthly arrangement with rent checks starts to look like one, and the answer changes your rights.
A seller in Middletown called me after a contractor priced out her kitchen. The estimate came back higher than the kitchen would add to her sale price. She’d been sitting on it for a month, embarrassed about the avocado-colored appliances and unsure what to do. We bought the house as it stood, appliances included, and gave her three weeks after closing to pack a home she’d lived in since the eighties.
Who’s drafting your agreement? That answer should be a Connecticut real estate attorney, every time. Valley Residential Group LLC can walk you through how an occupancy period gets set up on a Connecticut sale before you commit to anything.
Frequently Asked Questions
What Rights Do Tenants Have When a Connecticut Landlord Sells the House?
Selling the property doesn’t end a tenancy in Connecticut. The buyer steps into the landlord’s shoes, and an existing lease continues under its original terms until it expires. For a month-to-month tenant, the new owner has to properly end the monthly term and serve a notice to quit through a state marshal before filing anything in court. There’s no shortcut. Changing locks or shutting off utilities exposes a landlord to serious liability under Connecticut law.
When Is the Best Time of Year to Sell a House in Connecticut?
Spring and early summer bring the most buyer traffic across Connecticut, and listings in Fairfield County and the shoreline towns move fastest from April through June. Fall thins out, with price cuts clustering in late September and October as sellers get nervous about winter. If a job or a family situation drives your timing more than price, season matters far less than a buyer who can close when you need to. Our article on the best time to sell in Connecticut goes deeper.
What’s the Statute of Limitations for Foreclosing a Mortgage in Connecticut?
Connecticut didn’t have one until recently. A law signed in June 2025 and effective at the start of 2026 created a ten-year limit for foreclosure actions on certain mortgages secured by an owner-occupied one-to-four-family home. The clock runs from the earlier of the stated maturity or last-payment date and the last payment actually made. The same act shortened how long an undischarged mortgage stays valid as a lien. Important exceptions apply, including first mortgages recorded before the effective date, so read the Office of Legislative Research summary and review it with a Connecticut attorney.
How Long After Closing Can You Move Out of Your Connecticut Home?
Whatever you and the buyer put in the written occupancy agreement, within the ceiling the buyer’s lender sets. Financed Connecticut sales cap out at the federal owner-occupancy window described earlier, and many lenders cut that in half with their own overlays. A cash buyer has no such limit, so the timeline becomes a pure negotiation. Without a signed agreement, you have no right to stay past closing at all, however reasonable the request sounds.
Can a Buyer Charge Me Rent to Stay in the House After Closing?
Yes, and most do. The usual arrangement has you covering the buyer’s daily carrying cost, which includes loan principal and interest, property taxes, insurance, and association fees if the property has them. Short windows of a few days often get waived as a courtesy. For anything longer than a week, plan on paying, and plan on a refundable deposit held by the closing attorney.
If you’re weighing a sale in Connecticut and the timing is the hard part, not the price, I’m glad to talk it through. Tell me your situation, your dates, and what’s actually in the garage. I’ll give you a straight read on whether a rent-back, a delayed closing, or a cash offer with a flexible move-out fits best. No pressure, no obligation, and no hard feelings if you decide to list it instead.
Moving Out Around Hartford
Hartford County homes sold for a median of about $412,000 in the third quarter of 2026, according to SmartMLS. Plenty of sellers near the capital are lining up a next home at the same time, so a short occupancy window can take real pressure off the move. Our page for Hartford homeowners explains how we buy there.
Talk to Valley Residential Group LLC About Your Move-Out Date
Need a few extra days or weeks after closing? Contact Valley Residential Group LLC and we’ll talk through your timing with you, no pressure. You can also fill out the short form below.
Helpful Connecticut Blog Articles
- Cost To Replumb Your Connecticut Home
- Best Time to Sell a House in Connecticut
- Selling a Water-Damaged House in Connecticut
- Attorney Fees for House Closings in Connecticut
- Selling A Fire-Damaged House In Connecticut
- How To Successfully Sell A House With A Lien In Connecticut
- Cost to List on MLS in Connecticut
- How to Claim Ownership of Abandoned Property in Connecticut
- How to Sell an Inherited House in Connecticut
- How Long Can Seller Stay in House After Closing in Connecticut
- Can the Seller Back Out of a Real Estate Contract in Connecticut?
- For Sale By Owner in Connecticut
- How To Sell Your House And Successfully Move Out Of State
- Selling Your House During Bankruptcy