The house isn’t fully yours anymore. Not the day after you file, anyway.
That single fact trips up more Connecticut homeowners than any other part of the process. You still live there, mow the lawn, pay the taxes, and shovel the driveway after a February nor’easter rolls up I-91. Legally, though, the roof over your head belongs to something called the bankruptcy estate, and a court-appointed trustee has a say in what happens to it. I’ve bought houses from sellers in the middle of bankruptcy across Hartford County. The ones who come out ahead are the ones who learn the rules early instead of guessing.
Below is what that means for a Connecticut homeowner.
Who Owns Your House Once You File for Bankruptcy?
Think of it this way. The moment your petition hits the docket, an invisible container opens up and nearly everything you own drops into it. Lawyers call that container the bankruptcy estate. It includes your house, your car, your savings, and in some cases money you’re owed but haven’t received yet.
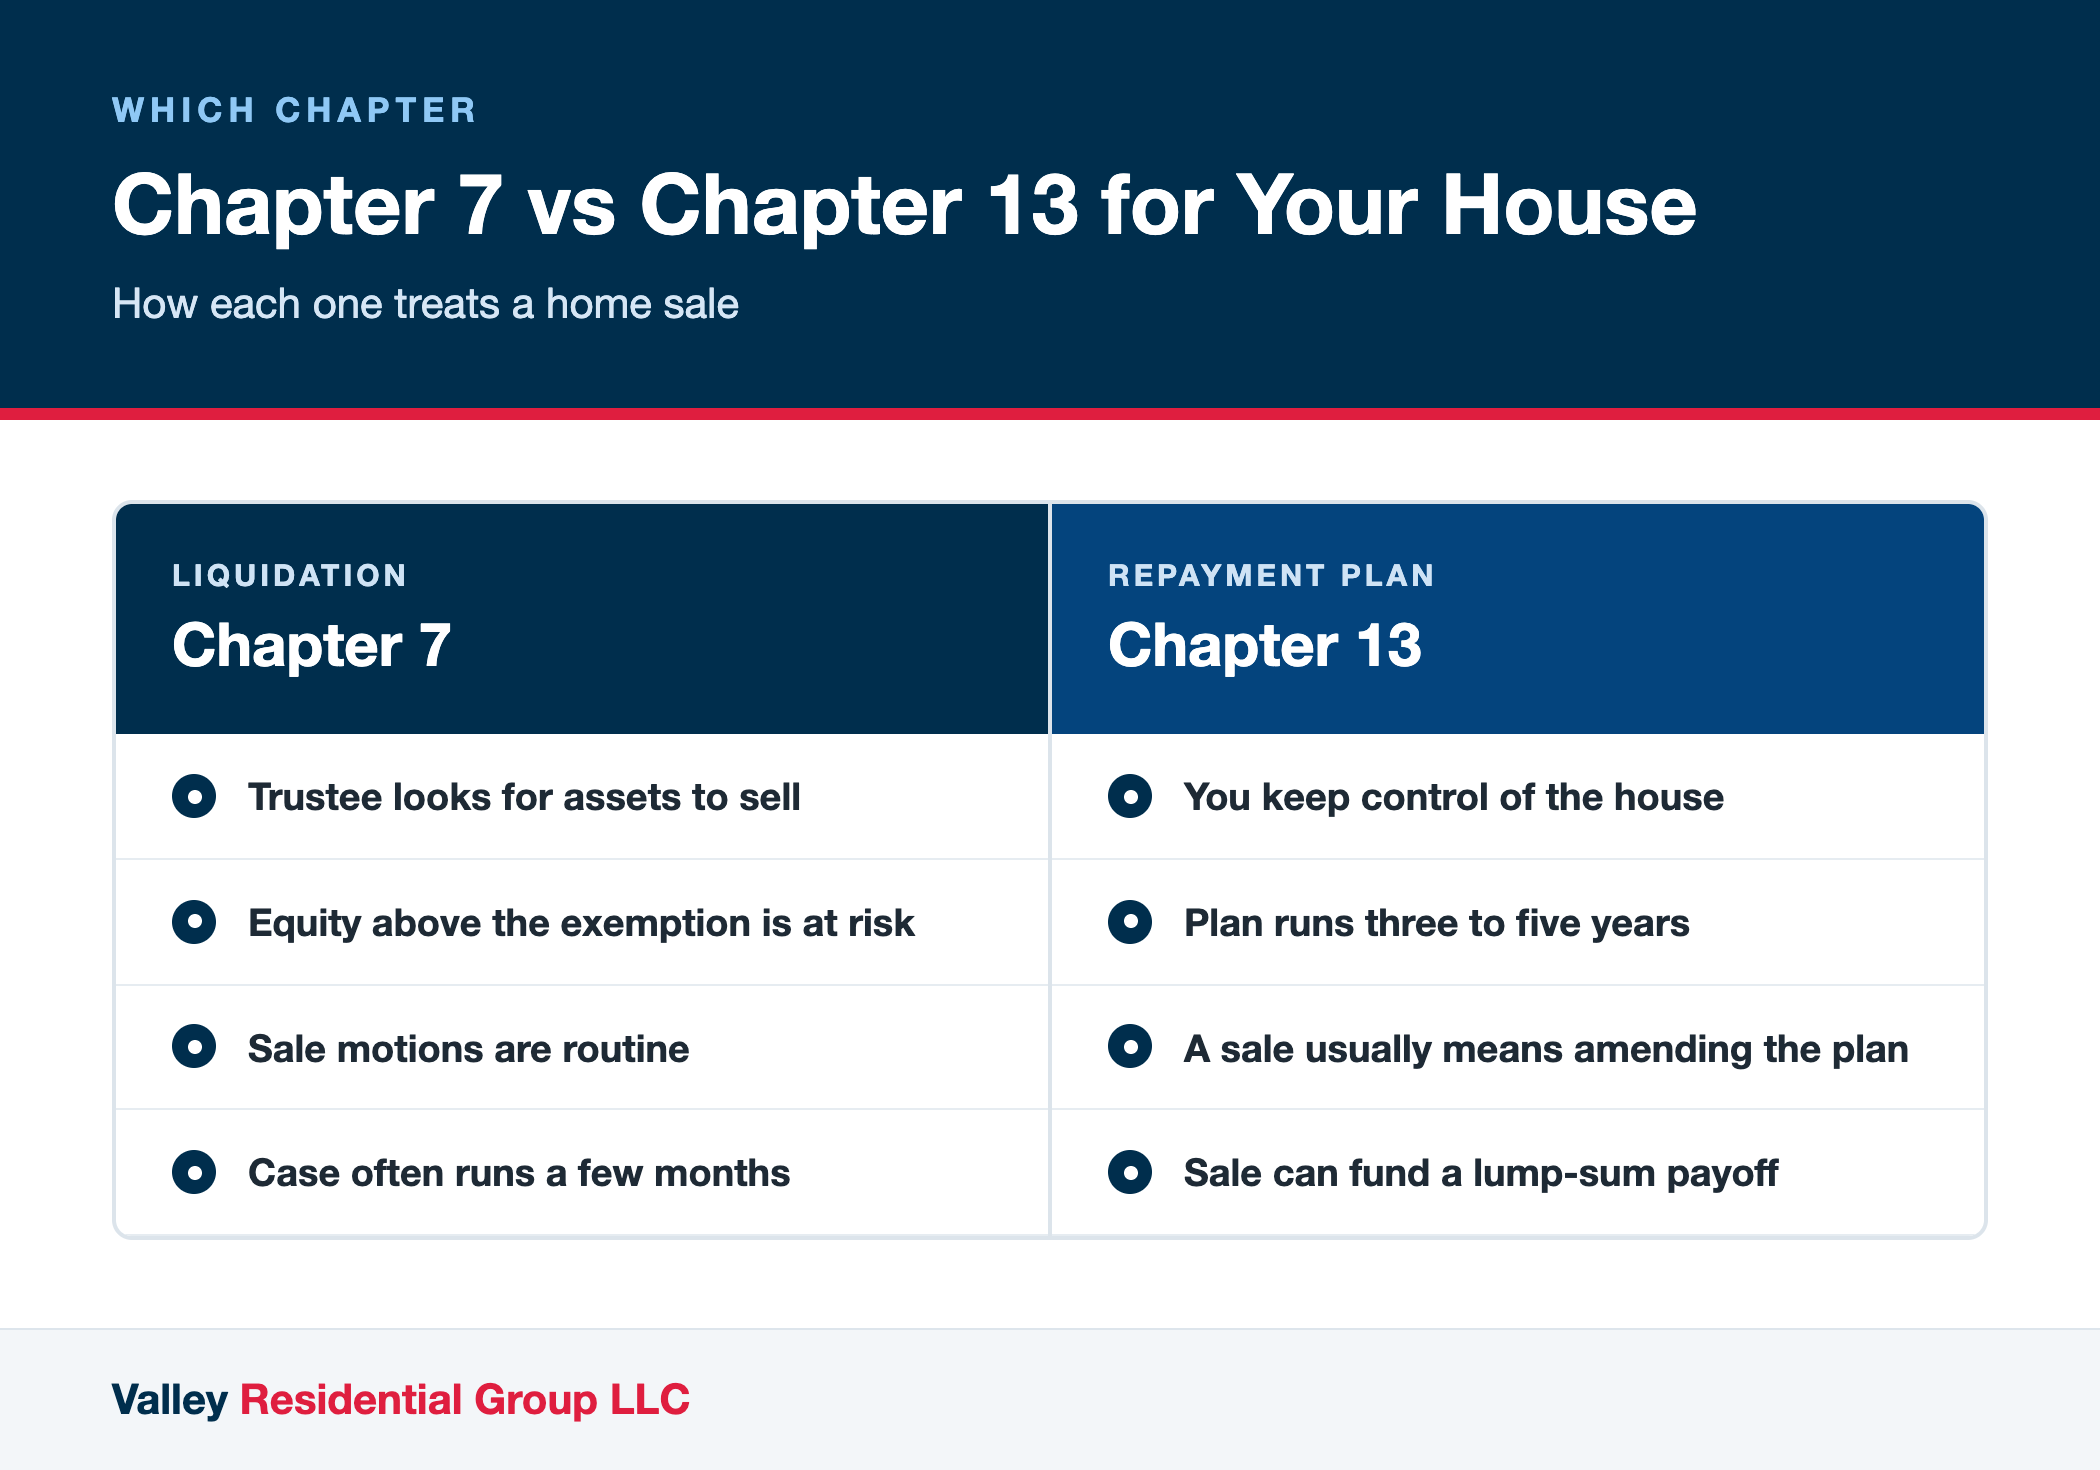
In a Chapter 7 bankruptcy, the trustee’s job is to find assets worth selling for your creditors. Under Chapter 13 bankruptcy, you keep control of the property while you work through a repayment plan, even though the estate still technically holds it.
Connecticut has a single federal bankruptcy district, but the court splits its work across three offices. Litchfield County and Fairfield County filers go to Bridgeport. Hartford, Tolland, Windham and New London County residents go to Hartford. Middlesex and New Haven County residents go to New Haven. The bankruptcy court’s own website lays out which office handles your county.
A while back, three siblings in Wethersfield called me about a two-family they’d inherited and never wanted. One of them was deep in a bankruptcy case, the tenants hadn’t paid in four months, and the garage was still full of their father’s lawn equipment. Nobody knew whether they were even allowed to sell. Once the sibling’s attorney got the trustee on board, we bought it as-is and the court signed off.
That’s the pattern I keep seeing in Connecticut. People treat bankruptcy as a wall between them and their property, when it’s closer to a supervised doorway. You can still walk through it. You just can’t walk through it alone, and the trustee holds the handle.
What Are Connecticut’s Bankruptcy Property Sale and Distribution Laws?
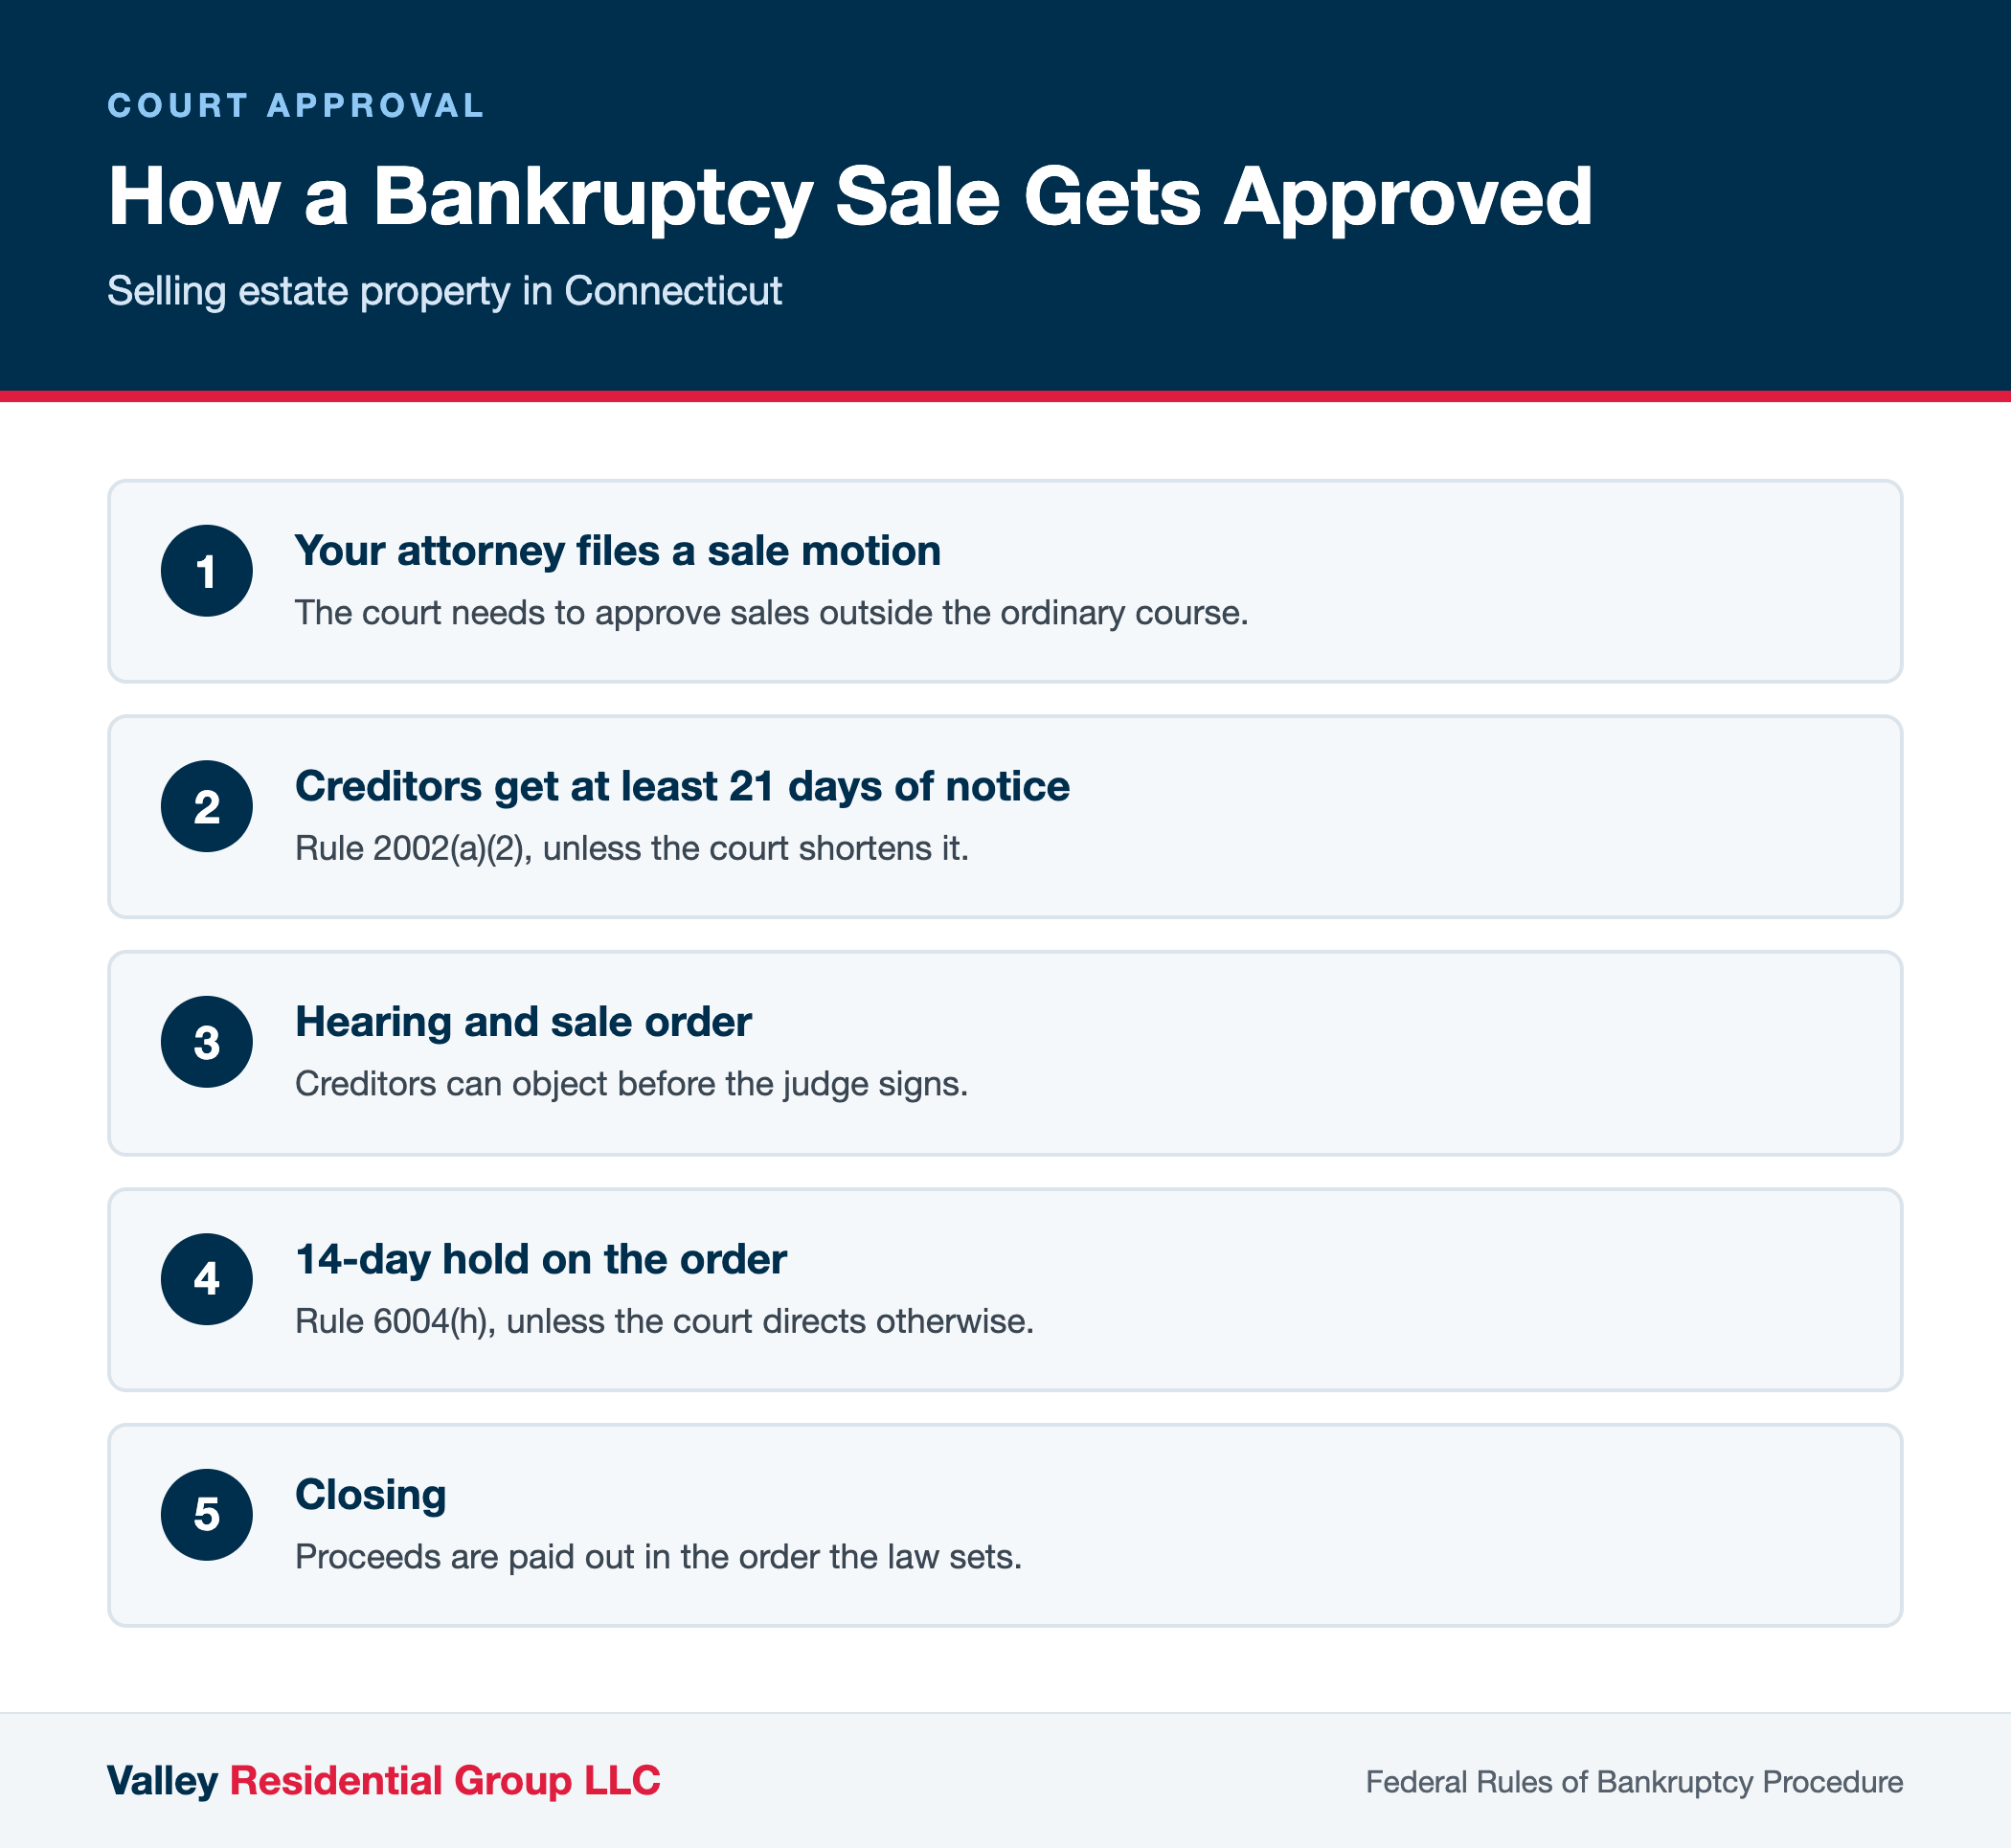
In a normal Connecticut sale, you sign a contract, the buyer gets a mortgage, and you close. Plenty of sellers walk into a bankruptcy case believing the same sequence applies. It doesn’t. Estate property sold outside the ordinary course of business needs the court’s blessing first.
Section 363(b) of the Bankruptcy Code lets a trustee or debtor in possession sell estate property outside the ordinary course only after creditors get notice and the court holds a hearing. Federal Rule of Bankruptcy Procedure 2002(a)(2) calls for at least 21 days of notice to all creditors before that sale, unless the court shortens the window for cause.
Twenty-one days sounds short until you add the steps around it. Your attorney drafts and files the motion. Creditors get their window to object. The judge signs an order. Rule 6004(h) then holds that sale order for 14 days after entry unless the court directs otherwise. Add it up and you’re looking at well over a month of pure procedure before anyone sits down at a closing table.
Proceeds get paid out in an order the Bankruptcy Code sets, not an order you pick. Secured creditors come first, so the mortgage holder gets paid, and property taxes owed to your town get satisfied too. Administrative costs follow. Whatever’s left flows toward unsecured debts like credit cards, personal loans, and medical balances, which are the bills most people file over in the first place.
Sellers who fight that order usually lose two months arguing with a trustee who is simply doing the job the Bankruptcy Code assigns.
Can You Keep Your Home Equity Exempt During Bankruptcy?
“Do I lose everything I’ve built up in this house?”
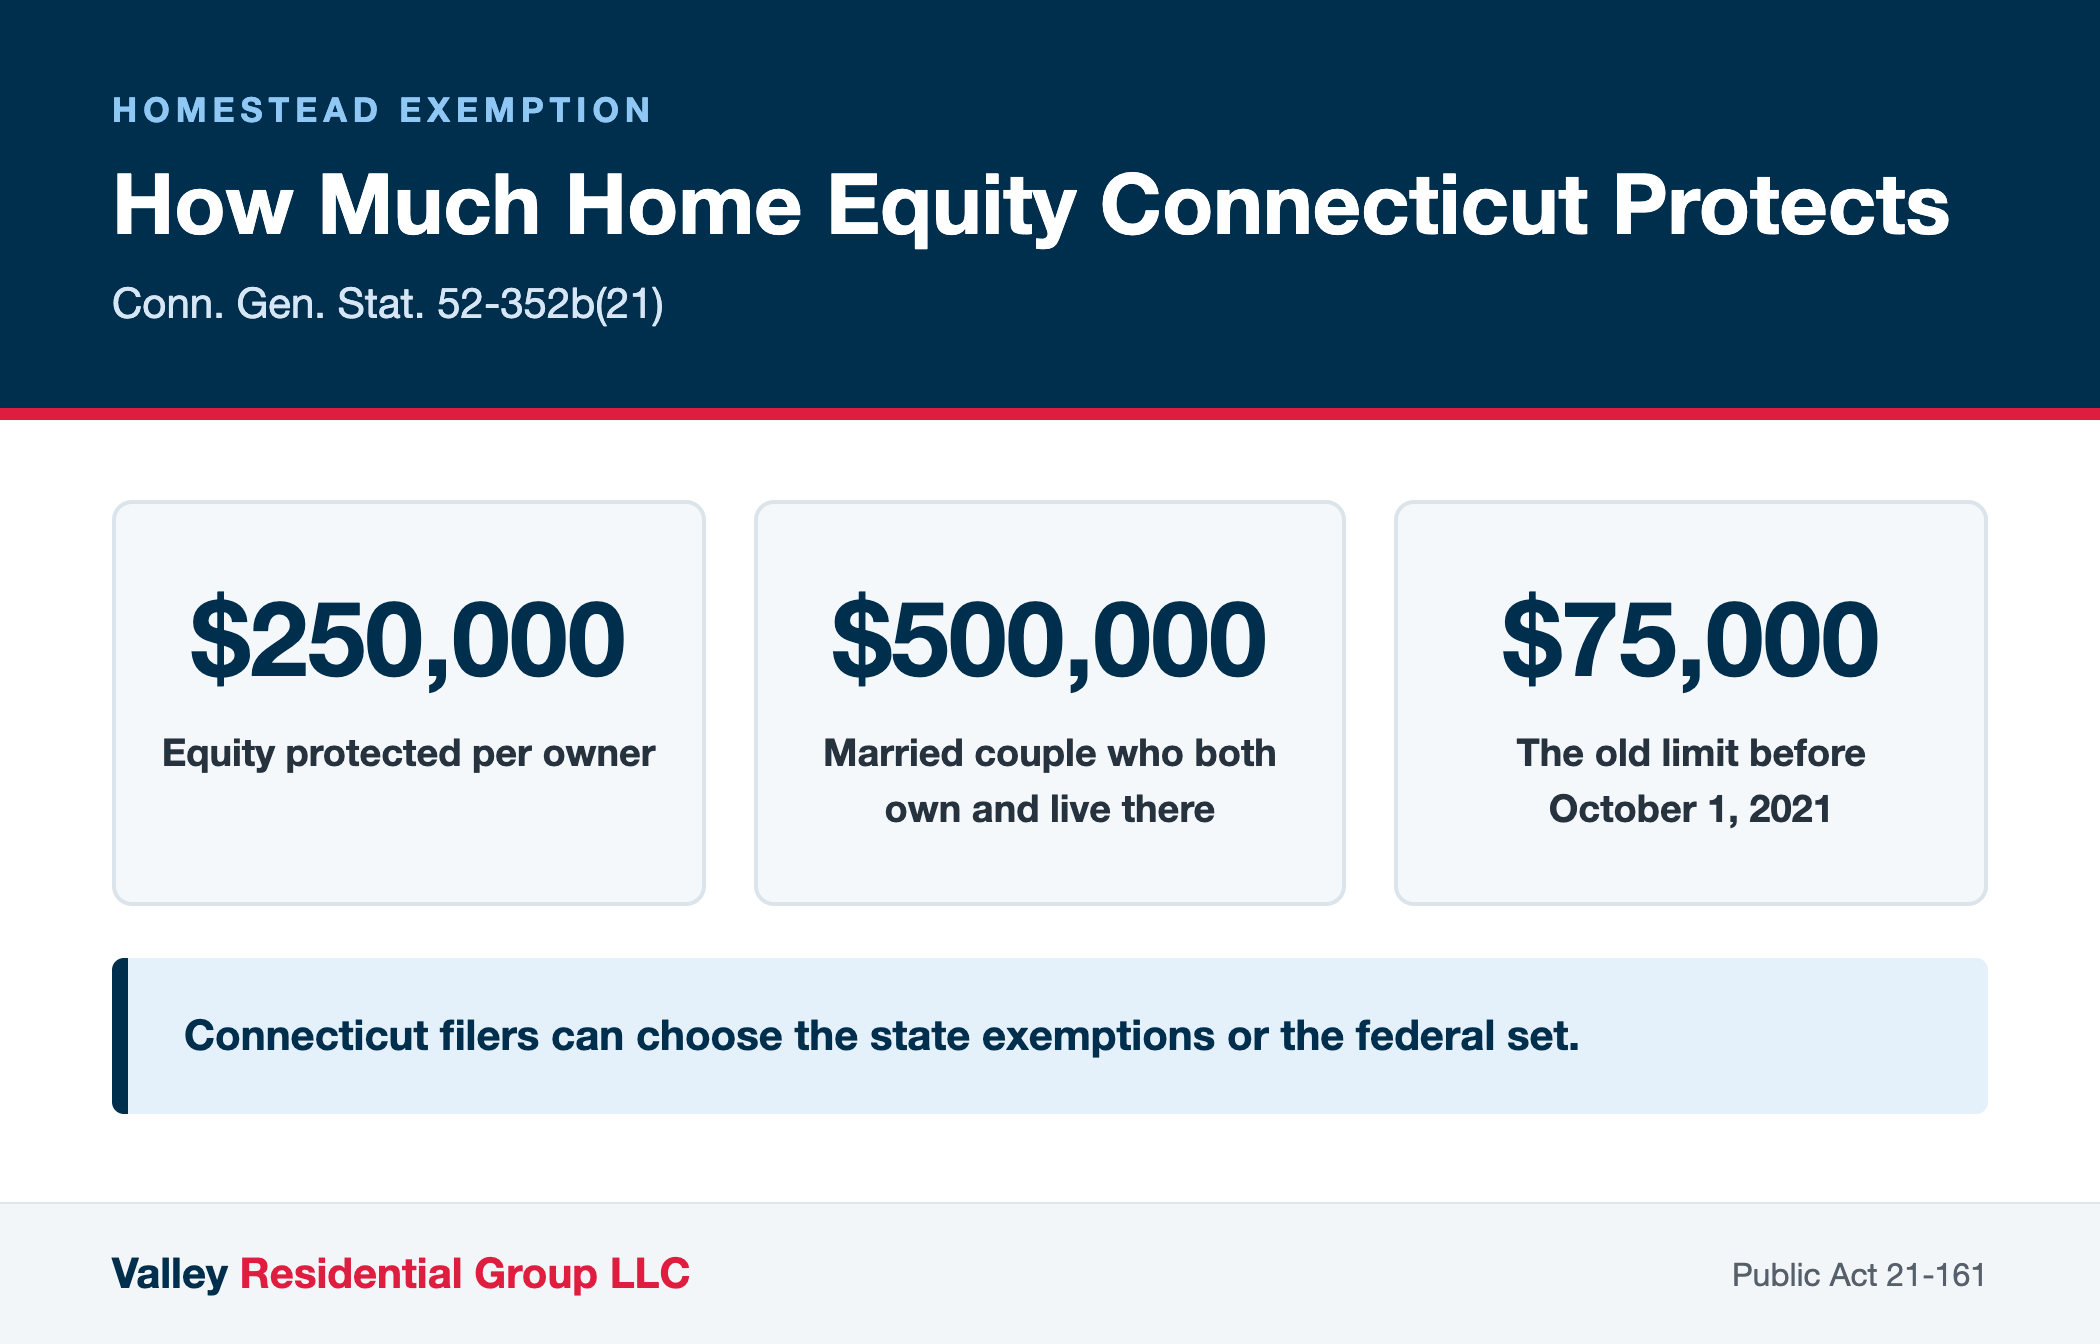
Probably not, and Connecticut is unusually generous here. The homestead exemption under Conn. Gen. Stat. 52-352b(21) shields up to $250,000 of home equity. Public Act 21-161 raised it from $75,000, effective October 1, 2021, and a married couple who both own and live in the home can protect as much as $500,000. You can read the exemption language in the state’s postjudgment procedures chapter.
So a Bristol colonial worth $400,000 with a $300,000 mortgage carries $100,000 of equity, comfortably inside the Connecticut shield.
This matters right now because Connecticut values have climbed. The statewide single-family median hit roughly $490,000 in September 2026, up 5.4% year over year. Homeowners who bought in Bristol or Meriden a decade ago often underestimate their equity when they first call a bankruptcy attorney, and that changes which chapter makes sense.
Connecticut also gives you a choice most states don’t. Filers here can pick either the Connecticut exemption set or the federal exemptions under 11 U.S.C. 522, because the state never opted out.
My opinion, after watching a lot of these play out, is that homeowners underestimate the homestead protection. Many rush to list before filing when they didn’t have to. Equity inside the exemption usually isn’t what the trustee is after.
Should You Sell Your House Before or After Filing Bankruptcy?
“If I just sell first, I skip all the court stuff, right?”
Sometimes, yes. Often it backfires. Selling before you file turns protected home equity into cash sitting in a bank account, and cash doesn’t get the same shelter the Connecticut homestead exemption gives real property. Spend that money on the wrong thing, like paying back a relative who loaned you money, and the trustee can claw it back as a preferential transfer.
Timing drives the whole decision. Connecticut’s market has been moving fast enough that a pre-filing sale can be realistic, so sellers aren’t necessarily stuck waiting out a slow bankruptcy. Single-family days on market stretched to 30 in September 2026, up from 25 a year earlier.
Waiting until after you file trades speed for cover. The automatic stay halts foreclosure the moment your bankruptcy petition is filed, so you get breathing room that a pre-filing sale never provides. If you’ve got a foreclosure sale date already set in Hartford Superior Court, that protection outweighs the extra paperwork.
Chapter 13 bankruptcy changes the math again, since a sale mid-plan can fund a lump-sum payoff and shorten your repayment plan.
When sellers ask me this directly, they get the same answer. The order of operations is a legal question, not a real estate question. Decide it with a bankruptcy attorney, then call buyers. Doing it backward costs people money in Connecticut every single month.
Can You Sell Your House During Bankruptcy in Connecticut?
Your buyer’s financing contingency and the court’s approval calendar run on separate clocks, and nobody warns you about the collision. Yes, you can sell during an active bankruptcy case. The hard part is coordination.
Most Connecticut contracts give a buyer 30 to 45 days to secure a mortgage commitment. Layer the motion, notice period, hearing, and post-order waiting period on top, and a conventional buyer’s rate lock can expire before the judge signs anything. Contracts die there.
Cash buyers solve the timing problem by removing the lender entirely. When I take on a bankruptcy-involved property, I write the contract so the closing date keys off the court’s order date rather than a fixed calendar day. That one change has saved more closings than any negotiating tactic I know.
A trustee reviewing your sale motion compares your contract price against recent sales nearby. A price that looks low against your town’s comps will draw questions, so get a realistic number before you sign. As of October 2026, a typical Connecticut listing spent about 42 days on the market before it sold or was pulled.
Valley Residential Group LLC works with Connecticut homeowners in exactly this spot. We buy as-is and hold patient closing terms while the court does its part.
One more thing about Chapter 13 bankruptcy. A sale usually requires your plan to be amended or your remaining payments recalculated, and your trustee will want to see where every dollar lands.
Can a Trustee Keep Your Bankruptcy Case Open Longer Than Expected?
Assume your bankruptcy wraps in three months and sign a lease that starts on schedule. You may find yourself paying rent on an apartment you can’t move into, with a trustee still working your file.
A Chapter 7 bankruptcy trustee can keep the case open to sell an asset, chase a transfer, or resolve a creditor objection. In Chapter 7, the trustee has a legal duty to collect and sell estate property, so sale motions are routine. If your Connecticut house carries equity above the exemption, that duty points straight at your home.
Any party can file a written objection during the notice period, and a single disputed claim can add weeks to your timeline.
What delays things most in Connecticut, in my experience, is title problems nobody knew about. Think of old town liens, an unreleased second mortgage from the early 2000s, or a probate gap from a deceased co-owner. Trustees won’t approve a sale into a messy title, and Connecticut towns don’t always process releases quickly.
Chapter 13 bankruptcy runs longer by design, typically three to five years of structured repayment. Selling midstream doesn’t automatically end the case. Your plan payments continue unless the court changes them, and the trustee decides how sale proceeds apply to what you still owe.
Plan a closing around best-case court timing and you’ll likely end up moving it.
What Happens to Your Sale Proceeds After Bankruptcy Closes?
A seller in Manchester closed on her ranch three weeks after her discharge order came through. She assumed the wire would land in her account that Friday. Instead it sat in her attorney’s escrow for another month while the trustee confirmed no unsecured creditors had remaining claims against the exempt portion.
Discharge and case closure aren’t the same event. Discharge wipes out the debts. Closure means the trustee has finished with every asset and filed a final report. Money tied to a bankruptcy estate typically moves after the second one, not the first.
Exempt proceeds come back to you. Money protected under the Connecticut homestead exemption stays yours, though some trustees want it documented clearly.
Proceeds above the exemption go to creditors in the order the law sets. That means the mortgage payoff, unpaid Connecticut property taxes, real estate commissions if you listed, administrative fees, and then unsecured claims. Agent commission is usually the biggest of the closing costs on a listed sale. I’ve seen that line surprise sellers who hadn’t budgeted for it. Going direct removes the commission line completely, which matters more when the remaining equity is thin.
A sale during bankruptcy can still trigger capital gains questions, and discharged debt sometimes generates a 1099-C. Those two items catch Connecticut sellers in April when the money is already spent.
Where does your money go if your case closes before the sale is done? Usually back to you, free of trustee oversight, assuming the property was abandoned from the estate.
Why Talk to a Connecticut Bankruptcy Lawyer Before You Sell?
For years I assumed a solid cash offer could rescue almost any situation. Bankruptcy taught me that a good price means nothing if the sale isn’t authorized.
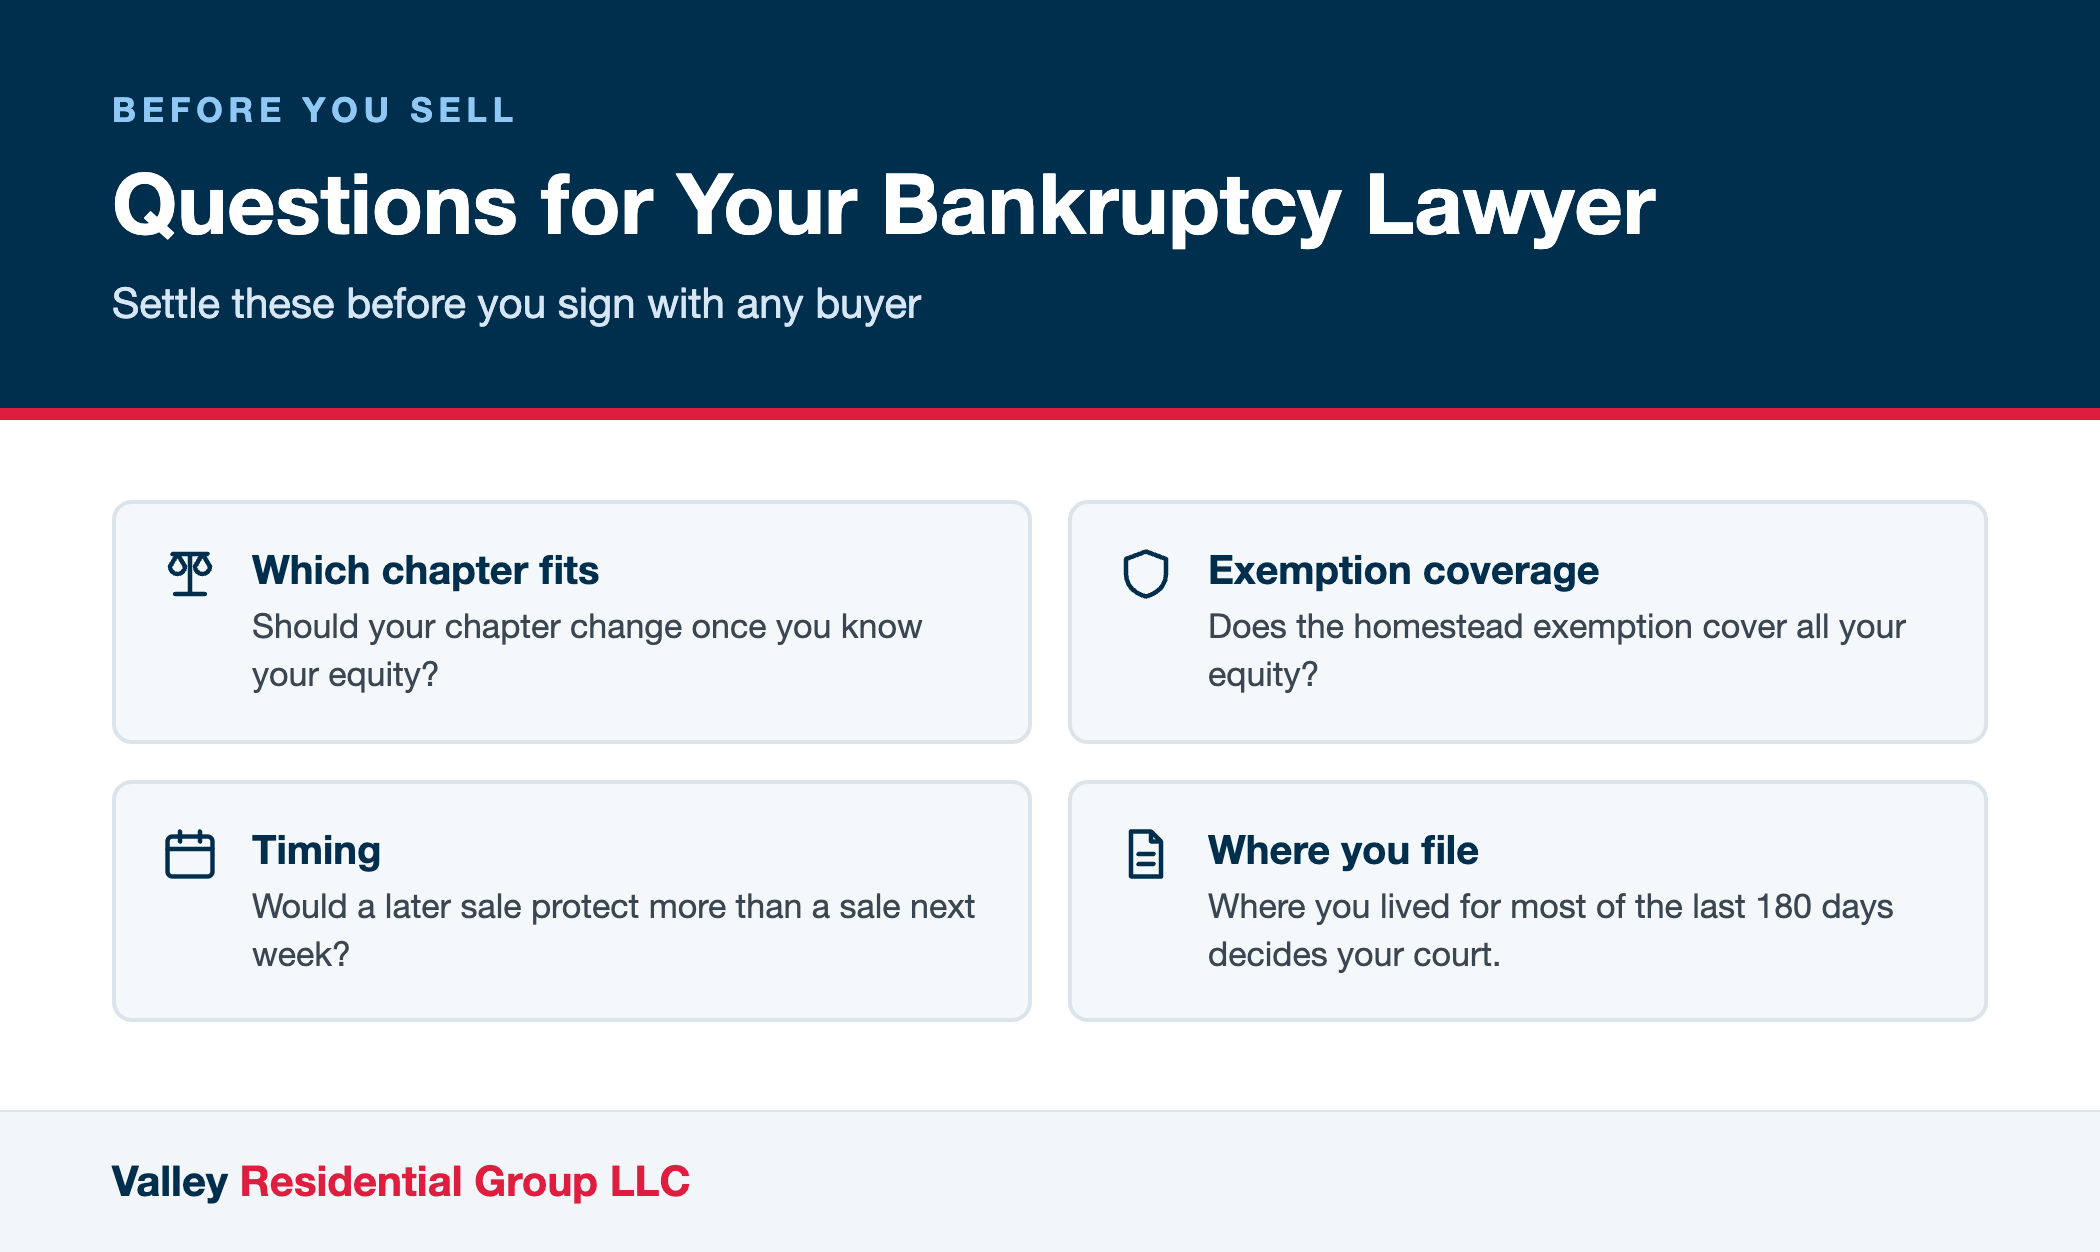
A good Connecticut attorney answers the questions that decide everything else. Should your chapter change? Does the homestead exemption fully cover your position? Would a sale three months from now protect more than a sale next week? Even where you file matters. You file in the district where you’ve lived for the greater part of the 180 days before filing, and that rule has tripped up people who recently moved into Connecticut from New York.
The cost is real but manageable. Connecticut bankruptcy attorneys handling consumer Chapter 7 cases commonly quote fees in the low four figures, and the court’s filing fee sits on top of that. Against a house carrying six figures of Connecticut equity, that’s cheap insurance.
A man called me on a Tuesday afternoon about his mother’s cape in Southington. She’d just moved into assisted living, he had a bankruptcy case of his own, and the basement still held her sewing machine and forty years of canning jars. We talked for twenty minutes. The most useful thing I did was tell him to call a lawyer before he signed anything with anyone, including me.
Good bankruptcy counsel works with your buyer rather than fighting them. They draft the sale motion, serve creditors, handle objections, and tell you honestly whether your Connecticut closing date is realistic. We routinely work alongside bankruptcy attorneys on these files, and you can see how our process works before you call. That keeps the paperwork moving instead of stalling between two offices that never talk.
Frequently Asked Questions
Do I Have to Tell My Buyer I’m in Bankruptcy?
Yes, and sooner rather than later. A buyer who learns about your bankruptcy case two weeks before closing will walk, because the approval requirement reshapes their whole timeline. Experienced Connecticut cash buyers handle court-supervised sales regularly and won’t flinch, but they need the information up front to structure the contract correctly.
Will the Trustee Take All My Equity If I Sell?
Not the portion your exemption protects. Connecticut’s homestead shield described earlier covers a large slice of equity for most homeowners in the state, and anything inside that limit comes back to you rather than going to creditors. Equity above the limit is what a Chapter 7 trustee pursues, which is exactly why running the numbers with an attorney before listing is worth the hour.
Can I Sell My House in Chapter 13 Bankruptcy Without Converting to Chapter 7?
You can. Selling during a Chapter 13 bankruptcy doesn’t force a conversion, though it usually means amending your confirmed plan so the trustee and court understand how proceeds apply to your repayment plan. Plenty of Connecticut filers sell mid-plan and finish their cases normally. The sale sometimes even moves up the finish line.
How Long Does Court Approval Actually Take in Connecticut?
The federal minimum notice period described above sets the floor, not the ceiling. Realistically, most Connecticut homeowners should budget six to ten weeks from signed contract to closing on a bankruptcy sale, assuming clean title and no creditor objections. Title defects and contested claims push it longer, so build flexibility into any moving plans.
Does Filing for Bankruptcy Stop a Foreclosure Sale on My Connecticut Home?
Yes, at least for a while. The automatic stay takes effect when your petition is filed and halts foreclosure proceedings immediately, including a scheduled sale date. That protection isn’t permanent. A mortgage lender can ask the court to lift the stay, and judges grant those motions when there’s no realistic path to repayment. Use the pause to make a decision rather than just delay one.
What If My House Is Worth Less Than I Owe?
An underwater property changes the trustee’s interest entirely, since there’s nothing left for creditors after the mortgage gets paid. Trustees often abandon these properties from the bankruptcy estate, handing control back to you. From there, a short sale or a sale with lender cooperation becomes the conversation, and your attorney can tell you which lenders in Connecticut move faster on those requests.
Should I Make Repairs Before Selling During Bankruptcy?
Spending money on a house you’re selling under court supervision rarely pays off. Money you pour into a new roof or a kitchen update may not come back in the sale price, and the trustee will want to know where it came from. Selling as-is sidesteps the question completely and keeps your remaining cash where it belongs, which is with you.
If you’re somewhere in the middle of all this and just want to know what your Connecticut house would realistically bring, we’re glad to talk it through. There’s no cost, no pressure, and no hard feelings if the answer is that you should hold tight and let your attorney finish the case first. Reach out whenever you’re ready.
Bankruptcy Sales in Connecticut
Connecticut homes sold for an average of about $305 per square foot in the third quarter of 2026, up 5.1% from a year earlier, according to SmartMLS data. Many Connecticut owners hold more equity than they realize, which shapes how a bankruptcy case treats the house. You can read how we buy houses across Connecticut.
Talk to Valley Residential Group LLC About Your Situation
Selling a house during bankruptcy? Contact Valley Residential Group LLC and we’ll go over your timeline and options with you, no pressure. You can also fill out the short form below.
Helpful Connecticut Blog Articles
- Cost To Replumb Your Connecticut Home
- Best Time to Sell a House in Connecticut
- Selling a Water-Damaged House in Connecticut
- Attorney Fees for House Closings in Connecticut
- Selling A Fire-Damaged House In Connecticut
- How To Successfully Sell A House With A Lien In Connecticut
- Cost to List on MLS in Connecticut
- How to Claim Ownership of Abandoned Property in Connecticut
- How to Sell an Inherited House in Connecticut
- How Long Can Seller Stay in House After Closing in Connecticut
- Can the Seller Back Out of a Real Estate Contract in Connecticut?
- For Sale By Owner in Connecticut
- How To Sell Your House And Successfully Move Out Of State
- Selling Your House During Bankruptcy